The Atlantic hurricane season runs from June 1 through November 30, and every Florida association should have a written plan in place well before the first storm forms. A good plan reduces damage, speeds recovery, and helps owners know what to expect. Two parts matter most: a mitigation plan that lowers risk ahead of time, and an emergency plan that guides communication and decisions before and after a storm.
This article is general information and is not legal or insurance advice. The association's attorney and insurance agent should be consulted.
Build a Mitigation Plan
Mitigation means taking action before a storm to reduce the damage it can cause. The work usually follows three steps:
- Identify hazards and weak points. Roofs, windows, doors, drainage, large trees, and loose items on common property should be reviewed. Flood prone areas and buildings with known problems should be noted.
- Take action in advance. Trees should be pruned to remove dead or weak limbs, drains and stormwater inlets should be cleared, and roofs and openings should be inspected and repaired.
- Record and share what works. Lessons from past storms should be written down and used to improve the plan each year.
Contracts for debris removal, tree service, water extraction, and emergency repairs should be arranged before the season begins, so that crews can be dispatched quickly once it is safe. Vendors are in high demand after a storm, and associations with agreements already in place are usually served first. Much of this preparation is handled by the person described in
facilities manager: what they do and why they matter.
Create an Emergency Contact and Communication Plan
The emergency plan should include current contact information for the board, the manager, key vendors, the insurance agent, and local emergency management. Owner and resident contact information should be updated each spring, including emergency contacts and whether the home will be vacant during the season.
The plan should also set out who is responsible for each task. Checklists commonly cover:
- Actions for the person designated to lead the association's response
- Tasks residents should complete before leaving, such as securing outdoor furniture and shutting off water
- Messages to send before the storm, during the event, and afterward
- A survey of the grounds and common areas after the storm
- Inspection of buildings and, in condominiums, units where access is needed
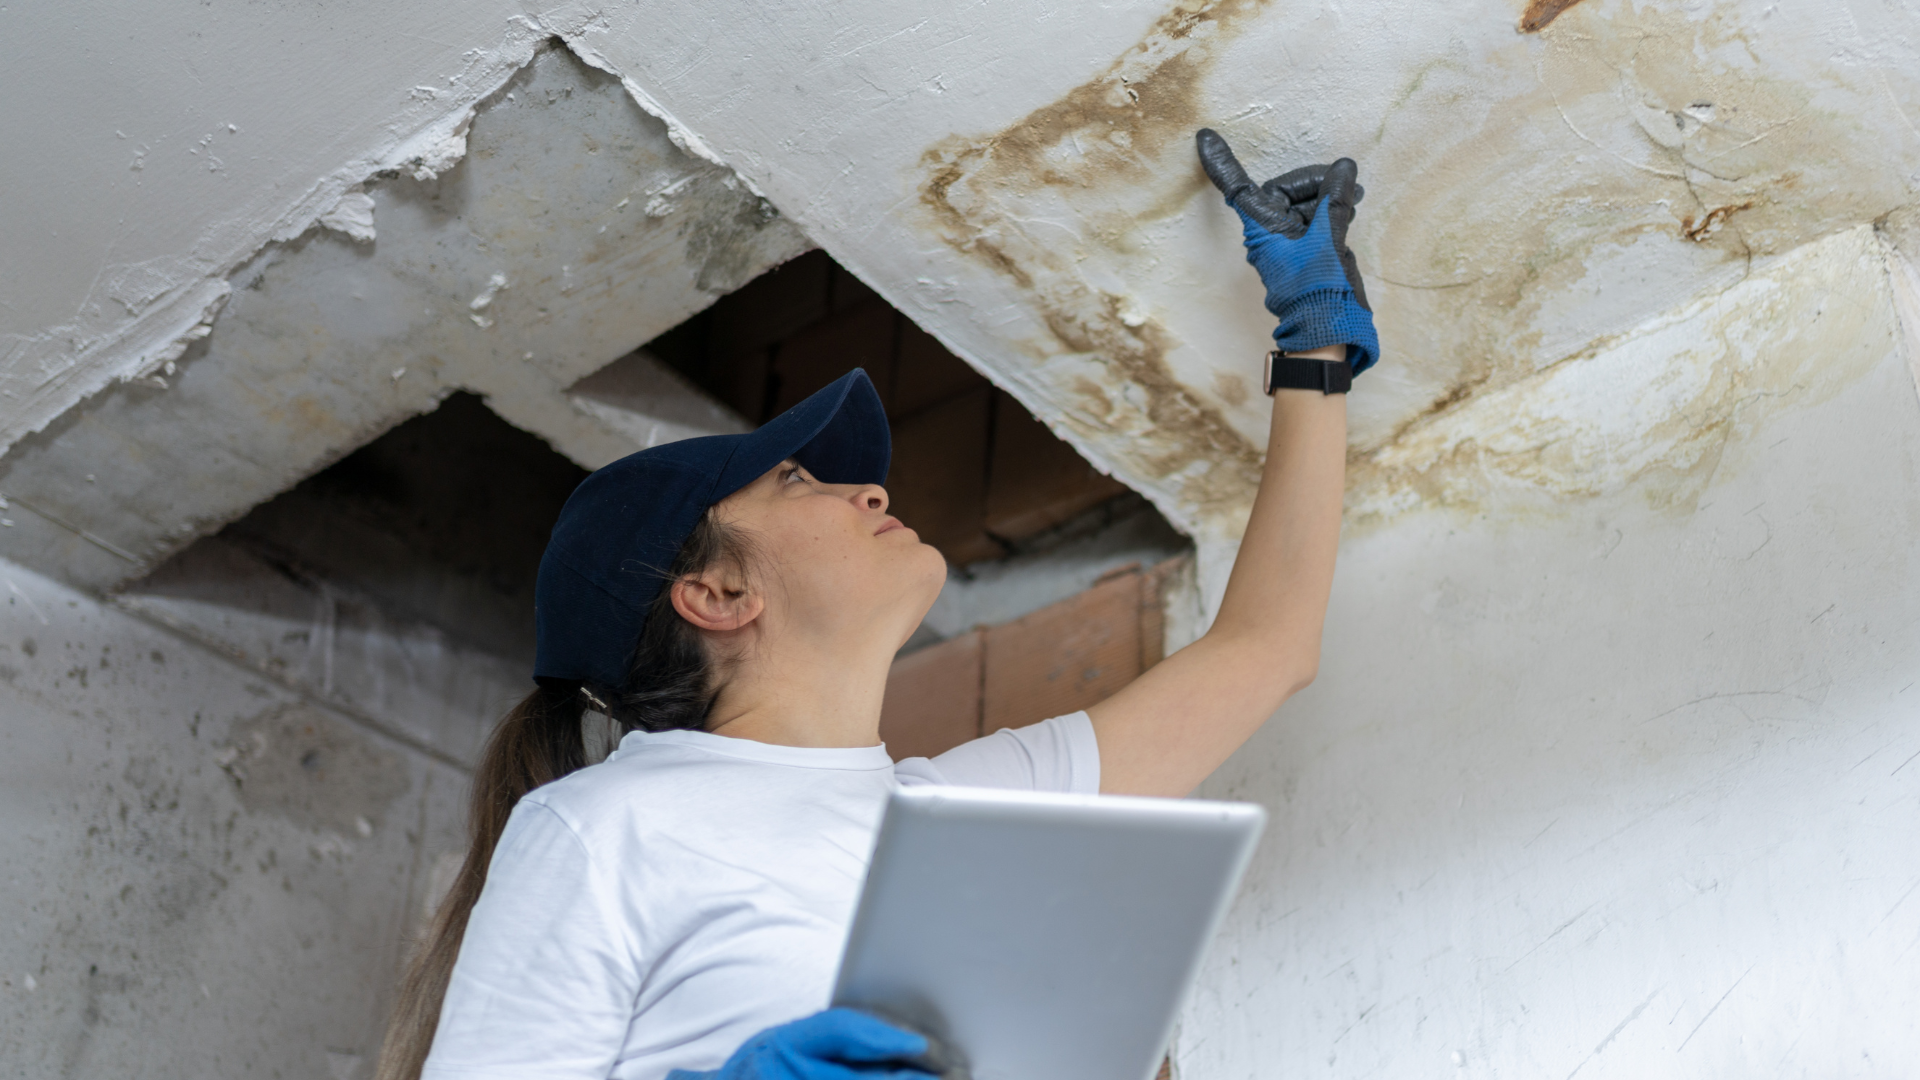
- Documentation of damage with photographs and video for insurance claims
A prepared notice can be sent when a storm approaches, reminding residents of the risks of staying and explaining what services may be unavailable. Owners should also be told what the association's insurance covers and what they are responsible for insuring themselves.
Understand the Board's Emergency Powers
Florida law gives boards additional powers when a state of emergency is declared for the area. These are found in section 720.316 for homeowners associations and section 718.1265 for condominiums, unless specifically prohibited by the governing documents. Among other things, the board may:
- Hold meetings by telephone or video with notice given as is practicable
- Cancel and reschedule association meetings
- Implement a disaster plan, including shutting off elevators, electricity, water, or other building systems
- Close parts of the property based on the advice of emergency officials or licensed professionals
- Contract for debris removal and mold prevention
- Levy special assessments without a vote of the owners
- Borrow money and pledge association assets to fund emergency repairs when operating funds are insufficient, without owner approval
In a condominium, the board may also require evacuation when an evacuation order is issued for the area. These powers are limited to the time reasonably necessary to protect health and safety, mitigate further damage, and make emergency repairs.
Know the Insurance Claim Deadlines
Under section 627.70132 of the Florida Statutes, a new or reopened property insurance claim is barred unless notice is given to the insurer within 1 year after the date of loss, and a supplemental claim must be reported within 18 months. For hurricane claims, the date of loss is the date the hurricane made landfall. Damage should be documented and reported promptly rather than waiting until the deadline. The importance of reserves for storm costs is discussed in
consequences of not having cash reserves.
Help Preparing Your Community
Hurricane plans, vendor arrangements, owner communications, and claim documentation are coordinated by Condominium Associates for the communities it manages. To talk about getting your association ready for the season,
contact us.